Categories
Media release

Absa uses AI and OCR technology to transform debt review process, accelerating support for customers in distress

Absa uses AI and OCR technology to transform debt review process, accelerating support for customers in distress

scroll for more

Absa has successfully implemented an innovative AI and Optical Character Recognition (OCR) solution within its Debt Review team, significantly improving the efficiency and accuracy of the debt review process for over-indebted South African consumers. Since implementation in late June, Absa has achieved a 41% increase in document indexing efficiency, enabling a one-day turnaround time for all new documents and emails.

The debt review process has traditionally been document-intensive, requiring information from multiple providers to be captured and processed manually. This created significant operational effort, longer turnaround times and a higher risk of human error. Through the implementation of an OCR/AI Gateway, Absa has automated the extraction and capture of information from standard document types. This enables documents to be processed automatically, reducing the need for manual intervention, improving accuracy and accelerating workflow initiation. The solution has also created a scalable platform for the future processing of more complex document types.

Kendrick Chauke, Absa National Manager for Debt Review, said: “The introduction of an AI/OCR solution in the Debt Review team has enabled us to automate manual processes and improve operational efficiency. While employees initially had questions about the impact on their roles, these were addressed through effective change management and engagement. Rather than replacing roles, this innovation has reduced repetitive tasks and allowed the team to focus on more value-adding activities that require skilled human expertise.”

The implementation has strengthened productivity and employee engagement, while improving turnaround times for customers going through the debt review process and contributing to a better customer experience. “These enhanced capabilities mark a significant step forward in Absa’s commitment to using AI technology to improve customer outcomes and drive operational excellence,” said Robert Benvenuti, Absa Chief Information Officer, Data & Applied AI.

With this move, Absa continues to explore opportunities to expand automation across its operations, reinforcing its position as a leader in digital innovation within South Africa’s financial services sector.

Categories
Media release

DHL Express and Absa Group Partner to Empower African SMEs across Sub-Saharan Africa

DHL Express and Absa Group Partner to Empower African SMEs across Sub-Saharan Africa

scroll for more

DHL Express, the world leader in international express shipping, and Absa Group, a leading pan-African financial services provider, have signed a Memorandum of Understanding (MOU) under DHL’s GoTrade initiative to support small and medium‑sized enterprises (SMEs) across Sub-Saharan Africa to trade beyond borders and unlock sustainable growth.

DHL GoTrade is an initiative designed to stimulate cross-border trade by enabling small and medium-sized enterprises (SMEs) to participate more effectively in global markets. The programme leverages existing logistics networks, expertise and partnerships to address key barriers to trade, including limited access to logistics knowledge, financing constraints, regulatory complexity and digital readiness.

The collaboration brings together DHL Express’ global logistics expertise and Absa’s deep banking and digital capabilities to provide African entrepreneurs with practical tools, training, and access to services that enable cross‑border trade, e‑commerce, and inclusive economic development.

Additionally, DHL Express and Absa will work together to introduce curated banking and logistics solutions designed for SME’s trading across borders, which will also support formal traders and businesses adopting green logistics or sustainable supply chain practices.

“Our main goal is to ensure we provide our African SMEs with the tools they need to access and participate in the global marketplace. This collaboration reflects our shared commitment to facilitate trade through SMEs,” said Hennie Heymans, CEO DHL Express Sub-Saharan Africa.  “By combining logistics expertise with financial and digital solutions, we are helping entrepreneurs move beyond local markets and build resilient, future‑ready businesses.”

As part of this collaboration, DHL Express will make available facilitators and trade lane experts to deliver logistics and cross-border trade training to SMEs within Absa’s wide network. Training will be based on the “Trade and Grow Beyond Borders” curriculum, which comprises 14 interactive modules that are delivered specifically to support SMEs at various stages of their lifecycle.

“SMEs are the engine of inclusive growth in Africa, creating jobs, strengthening communities and expanding the continent’s participation in global trade,” said Faisal Mkhize, Managing Executive for Business Development, Business Banking Pan-Africa. “Through our collaboration with DHL Express, we are giving our customers practical access to the trade knowledge, e-commerce capabilities and sustainable solutions they need to grow beyond borders and compete with confidence.”

The agreement also creates a framework for ongoing collaboration, allowing both parties to identify opportunities for new technologies, process improvements and innovations that enhance SME support, improve efficiency and strengthen the overall impact of the partnership across Africa.

Categories
Media release

Absa partners with the Totalsports Women’s Race to Champion Women’s Running

Absa partners with the Totalsports Women's Race to Champion Women's Running

scroll for more

The iconic Totalsports Women’s Race, which attracts more than 28 000 women across three major cities each year, is proud to announce a three-year partnership with Absa, which will see the leading African bank continue as the event’s Official Banking Partner, further strengthening its commitment to uplifting women, promoting wellbeing, and creating memorable experiences for thousands of women across the country.

“We are incredibly proud to announce Absa as the Official Banking Partner of the Totalsports Women’s Race,” says Michael Meyer, Managing Director of Stillwater Sports. “This exciting three-year partnership brings together like-minded brands that share a genuine commitment to empowering women, creating meaningful connections, and making a positive impact in the communities we serve. As one of South Africa’s most iconic Women’s Month celebrations, the Totalsports Women’s Race is about so much more than running – it’s about celebrating the strength, resilience, and achievements of women from all walks of life. We look forward to working alongside Absa to elevate the event experience and inspire thousands of women to come together across three major cities each August to celebrate the strength, resilience, and achievements of women.”

Highlighting the shared vision behind the partnership, Nikki Crous, Head of Marketing at Totalsports, says: “This exciting three-year partnership brings together brands that share a passion for empowering women and creating meaningful experiences. We look forward to working together to further inspire thousands of women across the country.”

Reinforcing Absa’s commitment to empowering women and strengthening communities, Jabulile Nsibanyoni, Head of Sponsorships, Brand and Marketing at Absa, says:

“The Totalsports Women’s Race is far more than a sporting event – it is a powerful celebration of women, their resilience, and their ability to inspire positive change in their families, workplaces, and communities. At Absa, we are committed to creating opportunities that empower people to realise their potential, and this three-year partnership reflects our dedication to supporting platforms that uplift and celebrate women. We are proud to join one of South Africa’s most celebrated Women’s Month road running celebrations as the Official Banking Partner and look forward to walking – and running – this journey alongside thousands of women across the country.”

EVENT INFORMATION: 2026 Totalsports Women’s Race

1.      Sunday, 02 August 2026

Totalsports Women’s Race Durban

Start Venue: Suncoast Casino, Snell Parade

Finish Venue: Suncoast Casino, Snell Parade

2.      Sunday, 9 August 2026

Totalsports Women’s Race Cape Town

Start Venue: 10km Start: Darling Street, Cape Town and 5km Start: Castle Street

Finish Venue: Grand Parade, Cape Town

3.      Sunday, 16 August 2026

Totalsports Women’s Race Joburg

Start Venue: Orange Road and Buffalo Road Junction, Marks Park

Finish Venue: Orange Road and Buffalo Road Junction, Marks Park

ENTRIES CLOSE:

Durban: ENTRIES HAVE SOLD OUT

Cape Town: ENTRIES HAVE SOLD OUT

Joburg: ENTRIES HAVE SOLD OUT

LIVE PERFORMANCE: Renowned for her electrifying performances and chart-topping hits spanning Kwaito, House, Gqom, Amapiano and Afropop, South African music powerhouse Busiswa will perform live at the Totalsports Women’s Race in Durban on Sunday, 02 August, Cape Town on Sunday, 09 August, and Johannesburg on Sunday, 16 August 2026, ensuring participants and supporters enjoy an unforgettable race-day experience both on and off the route.

CHARITY SUPPORT: The Totalsports Women’s Race proudly supports PinkDrive, a non-profit company (NPC) dedicated to increasing breast cancer awareness, providing education, and offering free services to medically uninsured individuals across South Africa.

Like our Facebok page:  Women’s Race / The PinkDrive

Follow us on Instagram:  Women’s Race / PinkDrive

Hashtag: #Totalsports #TotalsportsWomensRace #LoveTheRun #PinkDrive

WhatsApp Line: 064 815 4116

For more information on PinkDrive visit www.pinkdrive.org For further information on the Totalsports Women’s Race visit www.totalsportswomensrace.co.za

Categories
Our Voices

Why South Africa Deserves Our Optimism

Why South Africa Deserves Our Optimism

scroll for more

By Kenny Fihla, Group Chief Executive Officer at Absa

I was asked to give an honest assessment of where South Africa stands today. A simple question in phrasing, but one also so complex in its implication, and the kind the country has been wrestling with for years now, partly because as South Africans we have become accustomed to holding contradictory realities in our minds all at once: be it institutional fatigue alongside reform momentum, or deep scepticism alongside a persistent belief that the country is still capable of much more.

And while everyone’s perspective is shaped by their own lived reality, South Africa deserves a degree of optimism about its future.

The country has often struggled less with identifying the reforms required for growth than with sustaining the institutional coordination and execution needed to carry them through. And while progress has clearly been uneven, particularly across different sectors of the economy, there was at least growing evidence heading into this year that some of the country’s larger structural reforms were starting to move beyond intention and into practical effect.

We recently marked a full year without load shedding; logistics performance started stabilising after prolonged deterioration across rail and ports, resulting in record shipping volumes; and the South African Reserve Bank and National Treasury moved towards a lower inflation target in what was one of the most significant macro policy reforms in recent memory. None of this suggested the country’s deeper structural challenges had suddenly vanished, but together they were just some of the developments that contributed to the country’s first credit rating upgrade in twenty years.

Then came February 28.

The attack on Iran set off a chain of events that threw into disarray the global economic environment, mainly through the disruption of trade flows around the Strait of Hormuz, one of the world’s most critical energy and shipping corridors – creating exactly the kind of stagflationary pressure that becomes especially difficult for emerging markets like South Africa to absorb. The effects have been felt swiftly and broadly enough that there is little need to catalogue them individually, but the real question is what this means for an investment outlook that was only just on the upswing.

Investors will naturally become more cautious, particularly around sectors perceived to carry higher levels of leverage or uncertainty, while capital naturally gravitates towards areas where there is visible reform progress and stronger balance sheet resilience. We can already see some of this investment hesitation in our own portfolios at Absa, where a number of delayed drawdown facilities have been approved, suggesting that companies still want to invest but are becoming more cautious about taking the final step of fully committing capital in the current environment. At the same time, there is still strong appetite for high-quality South African investment opportunities. Absa’s own recent offshore debt capital market issuance, for example, was six times oversubscribed, which speaks to the fact that capital is still available and interest in South Africa remains significant when the underlying investment case is strong enough.

With that comes the recognition that many of the country’s hard limits on growth are now simply too large and too complex to be solved through the state or private sector acting independently of one another. The progress seen in electricity over recent years is one example of this, where private sector investment into renewable energy and independent power generation started feeding directly into the stabilisation of the broader energy system at a time when Eskom could not realistically have financed or delivered that transition on its own.

Similar models are now starting to emerge across logistics infrastructure, whether through private sector participation at the Durban container terminal, investment into rail capacity alongside Transnet’s existing network, or broader collaboration around freight and export infrastructure more generally. What matters in all of these cases is not just private participation for its own sake, but the creation of practical partnerships capable of improving the country’s productive capacity in ways neither side would likely achieve as effectively alone.

Much of this comes down to competitiveness: recognising that South Africa is competing for investment in a highly contested global environment, and yet we still have not fully grasped the urgency of positioning ourselves accordingly.

It may be difficult to think optimistically about growth in the current environment, but the past few years have shown that South Africa is still capable of moving in the right direction.

Categories
Our Voices

What Climate Disclosure Means for South African Insurers

What Climate Disclosure Means for South African Insurers

scroll for more

By Denver Fortuin, Chief Risk Officer Absa Insurance at Absa Group

Six months on from South African regulators putting in place a more structured approach to climate-related disclosure for insurers, expectations have begun to tighten in line with how other markets are approaching the same issue, with these risks now treated as having direct financial consequences for the sector. But while the case for doing so is clear, working through what this requires in practice will take time and will depend on the industry engaging more closely as it builds the capability to meet it.

In October last year, the Prudential Authority issued updated guidance on climate-related disclosures for insurers, grounding it more firmly in both international and domestic frameworks to align with global standards and reflect the move toward more consistent reporting, drawing on developments such as the G20’s Task Force on Climate-related Financial Disclosures and the International Financial Reporting Standards’ sustainability standards, while adapting the guidance to South Africa’s context.

The move comes from the recognition that climate change and the transition to a low-carbon, climate-resilient economy can affect the safety and soundness of financial institutions and the stability of the financial system, a reality that is particularly relevant in South Africa given its exposure to climate-related disasters such as droughts, floods, and wildfires, as well as transition risks linked to its reliance on fossil fuels for electricity, export revenues, and employment. There is broad agreement that rising global temperatures will influence the frequency and severity of weather-related events, with a growing share of natural catastrophe losses linked to these changes. For insurers, particularly those exposed to property and casualty risks, this places greater weight on how climate-related risks are assessed, priced, and managed.

At its core, the Prudential Authority expects insurers to treat climate disclosure as part of financial reporting.

Insurers are expected to show, among others, how climate risk is governed at board and management level, how it affects strategy, financial planning, and the value chain over defined time horizons, and how scenario analysis informs this. Climate risk must be integrated into existing risk management processes and firms must also quantify exposure and progress through appropriate metrics and targets, linked where relevant to remuneration, with disclosures grounded in local context and supported by internal controls.

But widescale implementation is easier said than done.

The guidance assumes insurers have access to granular, reliable climate data, yet emissions data from clients and investee companies is often incomplete, and local climate projections are still limited. Many insurers still rely on catastrophe models based on historical patterns, which do not fully capture how risks may evolve, introducing uncertainty into metrics and scenario analysis. At the same time, the skills required to interpret this information are not yet widely embedded. Much of this sits outside the traditional capabilities of many insurers, particularly smaller or newer entrants, and will require building expertise over time, whether internally or with external support. Embedding these considerations into how the business operates will also require internal change, including how boards engage and how policies and systems are structured.

These adjustments carry cost, and the ability to absorb that cost will differ across firms, and as a result, disclosures are likely to reflect varying levels of maturity, affecting consistency and comparability across the sector.

The constraints are shared, particularly where data is incomplete and capability is still developing, and progress will depend on how the industry works together to close those gaps, through closer coordination between insurers, regulators, and other stakeholders to improve the availability of usable data and bring more consistency to how climate risk is measured and disclosed – and this process cannot be deferred.

The Prudential Authority is clear that insurers are expected to begin now rather than wait for it to be legislated. Building the systems and internal capability needed for credible disclosure takes time, and it is more practical to do this steadily than under pressure. Judging by past experience with similar guidance, climate-related disclosures are likely to become mandatory, and the task now is to be ready for that.

Categories
Media release

Absa partners with Vault Strength Club

Absa partners with Vault Strength Club

scroll for more

As part of its Youth Month programme, Absa has partnered with Vault Strength Club (VSC), a leading Johannesburg-based running community, to champion youth entrepreneurship, wellness, and community connection.

The collaboration forms part of Absa’s broader commitment to active lifestyles, building on flagship initiatives such as the Absa Run Your City Series, while creating a platform that goes beyond fitness to celebrate purpose-led ambition.

At the heart of the activation is a focus on South Africa’s young entrepreneurs, small business owners, and emerging changemakers. The event will shine a light on the real stories, aspirations, and resilience driving the next generation, positioning it as more than a social run, but a meaningful celebration of youth-led progress and impact.

Participants will take part in a dynamic experience that blends fitness, culture, and opportunity. The programme includes a guided warm-up, live music, networking moments, an interactive Absa activation, and a 5km social run through Sandton. Attendees will also stand a chance to win vouchers from Absa Rewards partners, including Checkers, Puma, and Shell.

Through this partnership, Absa reinforces its role in enabling inclusive growth by supporting youth ambition, fostering entrepreneurial ecosystems, and creating spaces where communities can connect, thrive, and move forward together.

Categories
Media release

Absa Group announces new Pan-Africa Business Banking Chief Executive

Absa Group announces new Pan-Africa Business Banking Chief Executive

scroll for more

  • Absa strengthens Business Banking leadership across Africa to drive growth
  • Absa announces the appointment of Leon Barnard as Chief Executive: Business Banking across Pan Africa, effective 1 June 2026.

Johannesburg, South Africa – Absa Group, today, announced the appointment of Leon Barnard as the new Chief Executive: Business Banking across all our Pan Africa businesses, underscoring the critical role of Business Banking in driving sustainable growth, deepening customer relationships, and enabling economic participation across the continent.

Business Banking remains a core engine of growth for the Group, supporting entrepreneurs, small and medium enterprises, and commercial clients who are central to Africa’s economic development. This appointment reflects Absa’s continued focus on delivering integrated, scalable customer‑centred platforms and solutions, strengthening,  and scaling impact across key markets.

Leon is a senior banking executive with deep experience across business and commercial banking, customer strategy, and pan‑African operations. He has built a strong track record in leading large‑scale banking businesses across multiple markets, with a particular focus on delivering growth through customer‑centric propositions, product innovation, and scalable operating models. Leon is recognised for his ability to connect strategy to execution, building integrated banking platforms that support business clients, entrepreneurs, and growing enterprises across the continent.

He has held a number of senior leadership roles at Standard Bank Group, including leading Personal and Business Banking operations across Africa Regions, as well as roles in customer offerings and regional business leadership, giving him extensive exposure to diverse and complex African markets and client segments. His experience spans the full spectrum of banking services, from banking the unbanked markets, enterprise and SME banking to retail and commercial client solutions.

Commenting on the appointment, Kenny Fihla, Group Chief Executive Officer of Absa Group, said: “We are building a leadership team that combines deep experience with the ability to execute at pace. Strengthening our Business Banking franchise is a strategic priority for Absa, and this appointment ensures we have the right capability in place to drive relevance, competitiveness, and long‑term value for our clients.”

Categories
Our stories Our Voices

Banking on women is banking on Africa’s future

Banking on women is banking on Africa’s future

scroll for more

Across Africa, women are among the continent’s most powerful economic catalysts.  Women are starting businesses at the highest rates globally, sustaining SMEs and reinvesting earnings back into families and communities. Yet despite their contribution, women entrepreneurs continue to face systemic barriers to finance, leadership and opportunity.

In this thought leadership piece published by Forbes Africa, Prabashni Naidoo, Chief Governance Officer at Absa Group, explores why unlocking women’s economic agency is essential to Africa’s growth story. Drawing on insights from global economic discussions and Absa’s pan-African experience, the article makes a clear case: investing in women-led enterprises is a growth strategy.

As a purpose-led African financial institution, Absa remains committed to co‑creating inclusive systems that enable women not only to participate in the economy, but to shape its future.

A new wave of economic possibility is emerging across our continent. We are at an inflection point driven by millions of women who are building, trading and redefining the future of work. 

The entrepreneurial energy reverberating from Nairobi to Johannesburg is positioning Africa as a global growth frontier. However, unlocking the full potential of this economic force requires essential catalysts: equitable access capital, opportunity to lead, and systems that work for women.

Globally, women are not waiting for the future; they are actively building it. African women register the highest rate of entrepreneurial activity in the world, with nearly one in four starting their own business. They account for over 40% of SMEs and make up more than half of the continent’s self-employed workforce, contributing approximately 13% to Africa’s GDP. Yet, despite this undeniable economic presence, women-owned enterprises still face a financing gap exceeding $42 billion. This is not a reflection of their potential but of systems that have not fully adapted to the reality.

The issue is not simply access to capital; it is whether capital enters an ecosystem that enables women to convert opportunity into business stability, and stability into economic growth. Too many women entrepreneurs operate in informal or hybrid markets, often clustered in lower-margin sectors such as retail and hospitality, while higher-revenue industries like manufacturing, construction, and fintech remain male-dominated. As other African business leaders have also emphasized, investing in women is an investment in the other half of a country’s population. It is an opportunity to transform entire economies. This is not a moral appeal, but rather an economic truth that we should continue to grapple with until we see the change.

Leadership plays a decisive role in this transformation. There is a clear and positive correlation between women in leadership and a stronger focus on women’s financial inclusion. At Absa, we recognize that our ability to share inclusive economic outcomes begins within our organization. We drive women’s economic resilience through integrated financial and skills support, strengthened by Pan-African initiatives and strategic global partnerships.

Categories
Our stories Our Voices

SA Banks Are Already Using Agentic AI. Here’s Why It Matters for Customers

SA Banks Are Already Using Agentic AI. Here’s Why It Matters for Customers

scroll for more

By Lindelani Ramukumba

Rewind just a few years and large language models and generative artificial intelligence were barely on the public radar, yet the technology has already evolved into its next iteration: agentic AI, a new breed of systems that are semi- or fully autonomous and able to reason and act on their own. And adoption has skyrocketed, particularly over the past year.

According to a recent PwC survey, 79% of senior executives globally say AI agents are already being adopted in their organisations in one form or another, which is a striking level of uptake for such a nascent technology. One might assume that agentic AI has not yet reached South African shores, but it is already being implemented at scale, particularly in the financial services sector, where early deployments are delivering measurable gains in efficiency and productivity. For customers, it means faster service, more personalised interactions, quicker resolution of everyday banking needs, and less time spent navigating routine processes.

Take the customer acquisition stage as an example. Onboarding a small or medium-sized business has traditionally taken several hours spread across multiple days, with relationship managers collecting documents, verifying business registration, conducting Know Your Customer (KYC) checks, assessing credit risk, and configuring products across different systems. That level of manual work drives up the cost of acquiring each customer, which in turn limits how widely banks can serve the market, often forcing them to prioritise larger, higher-value clients over smaller businesses.

Now imagine compressing that process into roughly 20 minutes through automation, using tools such as biometric identity verification, automated Companies and Intellectual Property Commission (CIPC) lookups, real-time credit bureau integration, and instant KYC orchestration. Suddenly the economics change and banks can serve segments that were previously not viable at scale, expanding their addressable market and opening the door to far broader financial inclusion. For the SME owner, it means being able to open a business banking account in minutes rather than days, with far less time spent navigating paperwork and administrative processes.

Many banks across South Africa have already begun investing in these technologies, particularly in business-critical operations, and their application across other areas of the banking value chain is expected to expand considerably through 2026.

In September last year, Absa, for example, partnered with cloud-based customer relationship management platform Salesforce to bring its enterprise agentic AI solution, Agentforce, into Africa for the first time, a development that carries important implications for the banking industry.

As part of this, three autonomous AI agents are being tested within the bank.

The first is a co-pilot designed to support relationship managers. Historically, much of their time was spent preparing for meetings rather than engaging customers, with as much as 75% of the workday going into reviewing customer data across multiple systems, analysing recent transactions, identifying potential opportunities, and compiling engagement notes. Only about 25% of their time was spent actually interacting with customers. The AI agent now automates much of that preparation by generating pre-meeting briefs, pulling together customer information from multiple systems, highlighting relevant transaction patterns, and capturing notes after engagements. This has effectively flipped that ratio, with administrative time reduced by between 75% and 90%, allowing relationship managers to spend far more of their time focused on customers.

Another agent focuses on customer enquiries. It operates as a multilingual support assistant capable of responding to common banking questions across 11 languages, including isiZulu, Sesotho, and isiXhosa. Early results show that around 40% of customer service queries are now resolved without human intervention, meaning four out of ten interactions can be handled instantly while maintaining response quality. In many cases, responses that once took customers up to 30 minutes to receive are now delivered immediately, with success rates of close to 99%. The third agent focuses on monitoring and resolving technical issues across systems. Operating around the clock, it can detect and address many problems automatically, reducing the time it takes to restore services and allowing teams to focus less on operational troubleshooting and more on supporting customers. Since its introduction, the agent has already handled more than 6,400 internal support queries with a success rate of about 96%, meaning the vast majority of issues are resolved without needing to escalate to technical support teams.

These examples offer a glimpse of how agentic AI is beginning to change the way banks operate and, more importantly, what customers can expect in the near future.

It is likely that more of this technology will be used to expand digital onboarding, allowing customers to open accounts or access services far more quickly and with less paperwork. Banks may also begin using AI to assess creditworthiness in new ways, analysing transaction patterns and cash flow behaviour rather than relying only on traditional balance sheet information. For small businesses in particular, this could mean quicker access to financing and more proactive offers when their financial activity shows they are able to support additional credit. At the same time, many routine banking interactions are likely to move into digital self-service channels, allowing customers to resolve simple requests instantly while still having access to human support when it is genuinely needed.

Agentic AI is still in its early stages, but its direction of travel is already becoming clear.

As these systems mature and banks become more comfortable deploying them in everyday operations, customers are likely to experience banking that is faster, more responsive, and increasingly personalised. Much of this change may happen in the background, but over time it will transform how people interact with their banks.

Lindelani Ramukumba, Chief Information Officer and Interim Chief Digital Officer of Absa Business Banking

Categories
Media release

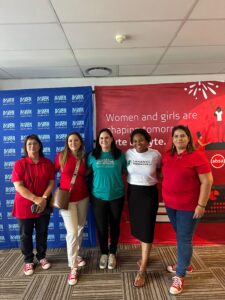
Phillipi Village buzzed with innovation this week as Absa, in partnership with Women in Tech South Africa, concluded a transformative hands-on-workshop aimed at demystifying Artificial Intelligence (AI) for local community members.

Phillipi Village buzzed with innovation this week as Absa, in partnership with Women in Tech South Africa, concluded a transformative hands-on-workshop aimed at demystifying Artificial Intelligence (AI) for local community members.

scroll for more

The session held at the heart of one of Cape Town’s most vibrant community hubs, marked a significant step in equipping the residents, particularly women and youth, with the tools to thrive in the digital era.

The workshop was designed as a technical lesson and as a platform for empowerment. Participants were guided through the practical applications of AI, exploring how technology can be leveraged to solve everyday challenges, enhance small businesses, and unlock new economic opportunities. By breaking down barriers to entry in the tech space, Absa and Women in Tech SA are actively fostering a more inclusive digital economy that directly benefits the surrounding Phillipi community.

This initiative is a powerful expression of Absa’s purpose – empowering Africa’s tomorrow, together, one story at a time – our deliberate intent to create shared value and ensure sustainable impact. The programme goes beyond skills transfer; it is fundamentally about enabling communities to tell their own stories. By providing access to cutting-edge technology and training, Absa is helping to ensure that Phillipi’s future narrative is written by its own residents using technology and innovation as a transformative agent.

“We believe that true transformation happens when we empower communities to shape their own destinies,” said Joy van Heerden, Chief Information Officer, Functions Technology at Absa Group. “True impact happens when innovation meets lived experience. By making emerging technologies accessible and practical, we’re helping communities move from participation to ownership—using digital tools not only to build businesses and livelihoods, but to tell their own stories and shape their own futures.”

The focus on women and children remains central to the partnership ethos. The workshop provided a supportive environment for female entrepreneurs and young learners to engage with AI, ensuring that the benefits of the digital age are equally distributed. “We are proud to partner with Absa Group for the fourth consecutive year ensuring that young people from the surrounding communities such as Nyanga, Mandalay, Crossroads, Philippi and Gugulethu have access to opportunities in the digital economy,” said Melissa Slaymaker, Africa Regional Director, Women in Tech, Global.

“This centre provides a safe, free space where youth can access computers, internet connectivity, and digital skills training, resources that many would otherwise not have. Each year, more than 6,500 young people benefit from programmes focused on digital literacy, AI awareness, entrepreneurship and job-ready skills,” Melissa commented.

She concluded: “Our mission is simple; we are ensuring that no young person is left behind in the digital age. Through this partnership with Absa, we are helping to unlock potential, build confidence and create pathways for youth to participate meaningfully in the future of work.”

From left – Right

Brigitte Muller, Absa

Jill Bachan, Absa

Melissa Slaymake, Women in Tech

Sandiswa Gwele, Ukhanyo Foundation

Janine Paulsen, Absa