Categories
Our Voices

Affordability and greater choice reshapes South Africa’s vehicle market

Affordability and greater choice reshapes South Africa’s vehicle market

scroll for more

17 September 2026

Affordability and greater choice reshapes South Africa’s vehicle market

Absa analysis shows changing price, growing competition and shifting consumer preferences are redrawing traditional vehicle segments

Affordability is driving a structural shift in South Africa’s vehicle market, with SUVs gaining significant ground as consumers increasingly seek competitively priced, well-equipped vehicles.

An analysis of 2.56 million new and used vehicle finance applications processed by Absa Vehicle and Asset Finance between January 2023 and June 2026 shows that SUVs increased their share of the combined SUV, bakkie and body-on-frame SUV market from 60.2% in the second quarter of 2023 to 67.6% in the second quarter of 2026.

SUV applications grew 38% between 2023 and 2025, while bakkie and body-on-frame SUV volumes remained relatively stable. By the second quarter of 2026, bakkies accounted for 28.9% of the three segments analysed, compared with 36.3% three years earlier, while body-on-frame SUVs represented 3.6%, down from 5.0%.

This growth has been supported by stable SUV pricing. The average SUV finance application value increased by only 0.6%, from approximately R350,000 to R353,000, over the period. By comparison, the average bakkie application value rose by almost 20%, from approximately R375,000 to R448,000, while body-on-frame SUVs increased by 14% to approximately R564,000.

Chinese vehicle brands have played a significant role in this shift, increasing their share of SUV finance applications from 19% in 2023 to 40% in 2026. Their growing presence has introduced greater competition and helped to maintain accessible pricing in the SUV category. Chinese brands have also more than doubled their share of bakkie applications, from 4.4% to 11.2%, although established manufacturers continue to lead the segment.

Charl Potgieter, Managing Executive, Absa Vehicle and Asset Finance says, “South African consumers are increasingly assessing the overall value offered by a vehicle, including price, features and suitability for their lifestyle. Greater competition in the SUV segment is giving customers more choice at accessible price points and is changing the composition of the market.”

While overall bakkie volumes have remained relatively stable, the composition of the segment is changing. Double cabs now account for 65% of bakkie finance applications, up from 58% in 2023, reinforcing their position as the dominant bakkie configuration.

At the same time, the half-ton bakkie share has declined from approximately 15% to 7%. Customer transition data indicates that former half-ton owners generally did not move to larger bakkies. Instead, 49% moved outside the bakkie and SUV categories, with hatchbacks becoming the most common next purchase.

“The decline of the half-ton segment has created a clear affordability gap for customers who need practical, entry-level mobility. Many of these buyers are choosing hatchbacks, sedans and panel vans rather than moving into more expensive bakkies,” added Potgieter.

Across the broader market, SUVs recorded the strongest customer retention, with 55% of existing SUV customers purchasing another SUV. Bakkie retention stood at 45%, while body-on-frame SUV customers were more evenly split between buying another body-on-frame SUV, moving to a bakkie or switching to an SUV.

“The traditional boundaries between vehicle categories are becoming less rigid,” says Potgieter. “A customer who arrives in one segment may leave in another, depending on what they can afford, the capability they need and the value available to them. Understanding what somebody currently drives is therefore only part of understanding what they may buy next.”

The analysis points to a market in which affordability, product availability and competition are becoming increasingly influential in vehicle-purchasing decisions. For consumers, this means greater choice in the SUV category. For dealers and manufacturers, it signals the need to align stock, pricing and customer engagement strategies with rapidly changing demand.


About Absa Group Limited

Absa Group Limited (Absa Group) is listed on the Johannesburg Stock Exchange and is one of Africa’s largest diversified financial services groups.

Absa Group owns majority stakes in banks in Botswana, Ghana, Kenya, Mauritius, Mozambique, Seychelles, South Africa, Tanzania (Absa Bank Tanzania and National Bank of Commerce), Uganda and Zambia and has insurance operations in Kenya and South Africa. Absa also has offices in the People’s Republic of China, Namibia, Nigeria and the United States, as well as securities entities in the United Kingdom and the United States, along with technology support colleagues in the Czech Republic.

Absa Group offers an integrated set of products and services across personal and business banking, corporate and investment banking, wealth and investment management and insurance. 

For further information about Absa Group Limited, visit www.absa.africa.

Media enquiries

Absa Group Press Office
Tsietsi Mahlasela, Tsietsi.Mahlasela@absa.africa
Categories
Our Voices

Agriculture Has Been Here Before, But Has It Learnt Its Lesson?

Agriculture Has Been Here Before, But Has It Learnt Its Lesson?

scroll for more

16 September 2026

By Abrie Rautenbach, Managing Executive for Agriculture at Absa CIB

Agriculture Has Been Here Before, But Has It Learnt Its Lesson?

In August 1971, Richard Nixon went on American television and announced to the world that the United States would stop converting dollars into gold. The decision marked the beginning of the end for the Bretton Woods era and sent currencies into a period of adjustment that was uncomfortable enough for richer economies and considerably less forgiving for developing ones, whose import bills could change dramatically through decisions made far beyond their borders. Two years later, amid another devaluation of the dollar and the upheaval surrounding the Arab-Israeli war, the oil-producing countries pushed crude prices sharply higher, with the export price index rocketing from 196 to 641. Oil had become vastly more expensive in the space of a year, and its reach through the economy meant that very little dependent on energy escaped untouched for long.

That had devastating consequences for agriculture in particular, as modern food production had become heavily reliant on fertiliser whose manufacture consumed enormous amounts of energy, while petroleum powered much of what came next, from the machinery working the land to the transport carrying crops away from it. Fertiliser prices tripled and, in some cases, quadrupled over the course of a year, adding heavily to the cost of producing food across the world.

Many parallels can be drawn between then and now, as conflict and disrupted trade routes once again feed protectionist instincts, unsettle supply and work their way into the price of the fuel and fertiliser agriculture cannot do without.

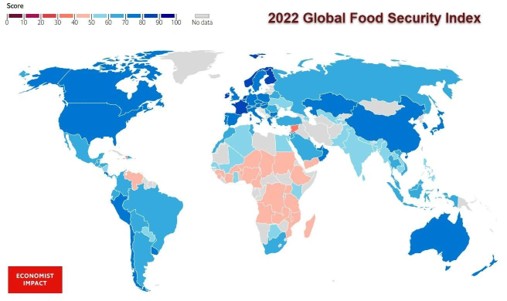
One observation has become hard to shake from conversations across the continent: food security now ranks among the top three priorities in almost every market we encounter through our work at Absa. Much of that concern comes down to affordability, because inflation is pressing on the consumer at the same time as it is making food more expensive to produce, which leaves agriculture carrying pressure from both ends of the chain.


Africa at 47.0, compared with a global average of 62.2. Source: Economist Impact, Global Food Security Index 2022

Food security ultimately depends on whether the agricultural value chain can keep functioning all the way back to the producer. Across much of Africa, millions of small-scale farmers rely not only on rainfall and markets, but on access to the right technology, finance, inputs and information to remain productive. Drought-tolerant seed, precision equipment, irrigation sensors and digital platforms such as Khula can improve resilience, optimise input use, reduce the cost to serve producers and connect farmers to finance, certified inputs and reliable markets. Technology is therefore becoming more than an efficiency tool; it is part of the infrastructure required to build a more resilient and commercially sustainable food system.

The same logic has implications for how banks think about agricultural businesses, because value in the chain does not always appear where a conventional credit model expects to find it. Take a wheat miller that buys once a year and has to hold enough stock to keep operating for months thereafter. The grain in the silo can be worth more than fixed assets, which means a balance sheet viewed too narrowly can look oddly weighted even when the economics of the business are sound. Structured trade and commodity finance allows the bank to recognise that reality by taking a view on the stock, with the maize or wheat in storage supporting the funding required to carry it through the cycle.

A poor year does not give an agricultural business the luxury of stepping away from the next one, because production has to continue and capital has to go back into the system before the damage from the previous season has necessarily cleared, and that changes how the bank judges the business quite considerably. The first task is to understand whether the strain belongs to the business or to the wider industry, because an agricultural client caught in a difficult cycle needs to be managed very differently from one whose problems originate within the operation.

When the strain is sector-wide, the discipline required of the business is fairly straightforward: protect the balance sheet, avoid overcommitting to capital expenditure and preserve enough cash flow to buffer against the next disruption. This is something we have been helping clients with more and more frequently. We have also seen how much resilience can depend on the commercial relationships a business has built before supply comes under pressure.

During the fertiliser shortages that followed Russia’s invasion of Ukraine, there was a period when supply became uncertain enough for us to ask some of our large CIB clients how they were thinking about allocation. Suppliers told us that customers who had been buying from them for decades would be looked after first, because those relationships had been built over time. A client who returned every year with a competing quotation and little history beyond price did not carry the same weight when stock became scarce.

Agriculture has always had to live with uncertainty, but the frequency and reach of recent shocks have made the cost of being financially unprepared much harder to absorb.

What followed the turmoil of the 1970s was a concerted effort to keep agriculture functioning, much of it focused on making sure producers could still get what they needed to keep producing and could finance it when markets tightened. Fifty years later, the circumstances are different, but the underlying lesson is familiar: agriculture copes with shocks far better when the financial and commercial capacity to keep producing has already been built.

The next dilemma may come in the form of the El Niño, which is expected to intensify through the second half of 2026 and affect different parts of the continent in very different ways. For some agricultural markets that may mean drought; for others, excessive rainfall and flooding. Either way, this is a moment for agricultural businesses to speak to their banks about whether their current financial position gives them enough room to carry the next season, and what support may be available if it does not.

Categories
Our Voices

Weak domestic demand and deteriorating export activity weigh on business confidence – Q3 Absa Manufacturing

Weak domestic demand and deteriorating export activity weigh on business confidence – Q3 Absa Manufacturing

scroll for more

15 September 2026

Weak domestic demand and deteriorating export activity weigh on business confidence – Q3 Absa Manufacturing Survey

Business confidence in the manufacturing sector deteriorated by 4 index points from the previous quarter, declining to a score of 27, the Q3 Absa Manufacturing Survey shows.

The sector remained under pressure during the third quarter of 2026, as weak domestic demand, deteriorating export activity and persistent economic uncertainty continued to weigh on business performance.

Domestic sales remained muted for a third consecutive quarter, while export sales declined by a further 6 index points compared to the previous quarter. Domestic and export orders also retreated by 7 and 5 index points respectively, while capacity underutilisation increased, pointing to greater spare capacity in the sector. Cost pressures eased somewhat, with the total unit cost of production declining from its second-quarter spike. Selling-price indicators, however, remained elevated and increased further. Yet these positive developments were insufficient to offset prevailing negative sentiment, with general business conditions continuing to trend downward.

Conducted between 13 and 24 August 2026 in partnership with the Bureau for Economic Research (BER) at Stellenbosch University, the survey was completed by approximately 700 manufacturing businesses. The confidence index ranges from 0 (no confidence) to 100 (extreme confidence).

“The Absa survey results reiterate the challenges arising from weak demand, difficult global trading conditions and lingering uncertainty following the sharp cost shock experienced in the second quarter,” says Sachin Chanderdhev, Sector Specialist: Manufacturing at Absa Business Banking. “While inflationary pressures appear to have moderated compared to previous years, consumers and businesses continue to carefully weigh their purchasing and investment decisions. Manufacturers thrive on operational continuity and maximum plant utilisation, and this is proving increasingly difficult in an environment characterised by subdued demand and weak sales.”

The survey shows that 66% of manufacturers identified insufficient demand as a key constraint within the current operating environment. Among the major subsectors, most recorded an overall decline in business confidence, with the exception of Metals & Machinery, which posted a 6-point increase to a confidence score of 31. Despite lower confidence scores, the Chemicals and Transport subsectors recorded a significant improvement in production levels, marking an encouraging recovery following two consecutive quarters of weak output. The Textiles subsector delivered the strongest sales performance, across both domestic and export markets, while export orders also surged during the quarter.

Despite challenging conditions, the sector continued to invest selectively, with fixed investment improving by 10 index points during the quarter. This relative resilience in capital spending is encouraging, particularly against the backdrop of weak demand and subdued confidence and suggests that manufacturers are still positioning for future growth rather than simply retrenching. The survey also points to a more constructive medium- to long-term outlook. Expectations for export volumes over the next 12 months improved by 10 points, while planned investment in machinery and equipment remains positive.

“Manufacturers continue to contend with elevated input costs, including fuel, labour and raw material expenses, which place pressure on profitability and cash flow management. Yet, the sector continues to demonstrate remarkable resilience,” reflects Chanderdhev. “Investment decisions are increasingly focused on improving efficiencies, eliminating unnecessary costs and strengthening competitiveness to capitalise on future growth opportunities as demand conditions improve.”

As the Bank of the Entrepreneur, Absa Business Banking remains committed to supporting Africa’s manufacturing sector through a comprehensive suite of financial and non-financial solutions. From funding working capital requirements and capital expansion projects to financing automation, digitisation and renewable energy initiatives, Absa partners with manufacturers to strengthen resilience, improve operational efficiency and unlock sustainable growth opportunities.

Beyond banking, Absa provides specialised sector expertise and tailored support solutions, enabling manufacturers of all sizes to navigate evolving market conditions and build sustainable businesses for the future.

Absa calls for investment execution to drive Uganda’s next growth cycle

London, 14 September 2026: Absa Bank Uganda is calling for greater focus on converting Uganda’s growing pipeline of investment opportunities into financed projects and productive businesses, as the country seeks to accelerate investment across energy, infrastructure, minerals, manufacturing and technology.

Attracting investor interest is only part of the challenge. Converting that interest into investment requires projects and businesses with the governance, cash flows, commercial structures and risk allocation needed to secure financing and move towards execution.

“Uganda has significant investment opportunities. The more important question now is how we convert that potential and investor interest into bankable projects and productive investment,” said David Wandera, Managing Director and Chief Executive Officer of Absa Bank Uganda. “The real test is whether we can build projects and businesses that can attract capital, withstand financial and commercial scrutiny and ultimately move into execution.”

Recent transactions demonstrate how this can work. In 2026, Absa provided a USD 50 million five-year facility to Uganda Electricity Distribution Company Limited, the utility’s first debt financing, to support investment in Uganda’s electricity distribution network. The investment is expected to enable more than 200,000 additional electricity connections.

Absa also partnered with the Uganda Energy Credit Capitalisation Company on a UGX 11.085 billion concessional credit facility, providing capital for onward lending to eligible energy companies. The structure shows how commercial and development finance can work together to address financing constraints and move capital towards productive investment.

These transactions build on Absa’s financing and advisory activity across telecommunications, sustainable real estate, green mobility, waste management and capital markets, including participation in a USD 100 million syndicated facility for MTN Uganda and its role as Lead Transaction Advisor on Airtel Uganda’s IPO.

“The opportunity is to connect more capital with the right opportunities and create the conditions for that investment to succeed,” Wandera said. “Different projects require different types of capital. The role of banks is increasingly to understand what an opportunity needs, structure it appropriately and connect international capital with the local knowledge and execution capability required to make it work.”

Uganda’s strengthening financial markets provide a foundation for that investment. The country has risen from tenth when the Absa Africa Financial Markets Index was launched, to third in the 2025 Index, reflecting progress in the financial ecosystem available to support investment and growth.

Wandera made the case for greater investment execution at the UK-Africa Investment Summit in London on 11 September, where discussions focused on moving African economies from access to production. He contributed to discussions on institutional finance and financial infrastructure, alongside a closed working session on critical minerals and industrial value addition.

“Uganda’s next investment story is about translating growing opportunity into investment that strengthens businesses, infrastructure and long-term productive capacity,” Wandera said.

Categories
Our Voices

When Cash Cannot Move: Why Treasury Is Becoming Central to Africa’s Growth Strategy

When Cash Cannot Move: Why Treasury Is Becoming Central to Africa’s Growth Strategy

scroll for more

7 September 2026

By Themba Rikhotso, Managing Executive, Transactional Banking, Absa CIB

When Cash Cannot Move: Why Treasury Is Becoming Central to Africa’s Growth Strategy

The global financial crisis left corporate treasurers with an uncomfortable truth that money which appears to be available can dissipate rather quickly when everybody reaches for it all at once. Companies that had treated liquidity largely as a balance-sheet management issue discovered how much depended on being able to get hold of cash when markets stopped behaving normally, and the years that followed produced a treasury function far less willing to take that access for granted, particularly where buffers were thin or too much confidence rested on a handful of banking relationships and funding lines that had never been tested under real strain. In that sense, 2008 did its job, teaching companies to worry about whether the money would be there.

Nearly two decades later, we are seeing that the money can be there and still prove surprisingly hard to put to work.

Cross-border payments are becoming technologically faster at the same time that the financial system around them is becoming more politically and economically fragmented, leaving companies with a curious problem: they can know where their cash is almost instantly and still face growing uncertainty over how freely it can move. Hard-currency shortages can complicate conversion in one market, regulation can change the economics of moving funds in another, while the correspondent relationships that have traditionally carried cross-border payments have themselves become thinner in parts of the world. None of this necessarily reduces the amount of cash on the balance sheet; it changes the degree to which that cash can be relied upon as immediately deployable liquidity.

Research suggests treasury has already spent years improving the things it can control from the inside out, investing heavily in automation and tighter control over cash. PwC’s 2025 Global Treasury Survey found that 94% of respondents already operated a dedicated treasury management system and 65% planned to expand their use of APIs, but forecasting still relied heavily on manual consolidation even among large companies and satisfaction with forecasting remained worryingly low.

EY found something similar, just from a different angle: 73% of respondents still described digitising treasury functions as a challenge, even as the technology moves towards real-time liquidity management and increasingly automated payments.

The interesting part is the mismatch. Companies are getting progressively better at seeing cash and processing it, while the practical conditions governing whether that cash can be moved are becoming more complicated, which means the industry may be perfecting the tools for yesterday’s problem just as the problem itself is changing shape.

That should trouble treasurers because much of the operating logic built after the last great liquidity shock was designed to make cash easier to control from the centre. There was good reason for that, and there still is, though an arrangement can be beautifully efficient while everything is working and rather less impressive once one of the routes on which that efficiency depends becomes constrained. That is where transactional banking starts to earn a more strategic place in the conversation, because the bank sits in the actual pathways through which liquidity moves and can see where those pathways narrow.

A company may have perfectly sound liquidity at group level and still find that the route between one market and another has become slower or more expensive than the balance sheet suggests, which makes the banking architecture around that cash more consequential. The value of the transaction bank then is in helping the client understand the shape of that architecture across jurisdictions and, just as importantly, where it is likely to fail under pressure.

This is also why the old language of global consistency can be misleading. What we are hearing from clients at Absa is that the real difficulty is in making decisions across different markets that still add up to one coherent treasury strategy. That becomes harder when each market imposes its own operating conditions and payment realities, and it places a premium on banks that can hold the whole picture while still understanding the detail on the ground.

What companies really need is consistency of outcome across markets that are anything but consistent in how they regulate and clear transactions. That asks more of the banking relationship than the ability to provide the same product everywhere. It asks the bank to join up local knowledge with a broader view of the client’s liquidity, so that cash management reflects how money actually moves through the business. At that point, transaction banking becomes part of the company’s resilience architecture, because the way liquidity is structured begins to determine how much freedom the business has to act.

The ability to facilitate trade, optimise liquidity, strengthen supply-chain ecosystems, support cross-border commerce and enable efficient movement of capital is becoming a critical differentiator for financial institutions seeking to create long-term value for their clients and shareholders.

2008 pulled treasury much closer to the question of survival. The period ahead could pull it further upstream, into decisions about where a business can realistically grow, because a market is only as accessible as the company’s ability to fund activity there and bring the resulting cash back into productive use. Once liquidity starts influencing where expansion is practical, treasury stops sitting behind corporate strategy and starts helping determine the map on which that strategy can be executed.

Categories
Media release

Every flavour. Every beat. Every story matters: Absa announced as headline sponsor of Delicious Food & Music Festival in partnership with SABC

Every flavour. Every beat. Every story matters: Absa announced as headline sponsor of Delicious Food & Music Festival in partnership with SABC

scroll for more

Absa is proud to announce its headline sponsorship of one of South Africa’s most loved lifestyle experiences, ushering in an exciting new era for the Absa Delicious Festival in partnership with SABC.

More than a festival, Delicious is where people come together: around a table, beneath the stage lights, through a favorite song, a memorable meal, a new discovery or a moment shared with the people who matter most. It is a platform where cultures meet, talent shines and stories unfold. And because at Absa, Your Story Matters, the bank is investing in an experience that celebrates the stories that make South Africa remarkable.

The Absa Delicious Festival in partnership with SABC will take place at the iconic Kyalami Grand Prix Circuit on 10 and 11 April 2027. Festivalgoers can look forward to an unforgettable  weekend of world-class entertainment, exceptional food, cultural expression and the best of South African and international talent.

Through the partnership, Absa will bring their customers closer to the experiences they love, with exclusive benefits, added value and new ways to enjoy the festival. Further details, including artist announcements, ticket information and customer experiences, will be revealed in the months ahead.

“South Africans have a remarkable way of turning moments into memories and memories into stories,” says Candice Thurston, Managing Executive for Brand and Marketing at Absa Group. “Whether it is the song that takes you back, the meal shared with people you love, or the thrill of discovering a new artist, these are the moments that stay with us. They remind us who we are, where we come from and what connects us.”

“At Absa, we believe that Your Story Matters. Our partnership with Delicious is therefore about much more than a name on a festival. It is about creating meaningful opportunities for our customers and communities to experience the music, food, creativity and culture that move them. It is about championing the artists, chefs, entrepreneurs and creators whose stories deserve to be seen, heard and celebrated.”

A bigger stage for African stories

For years, Delicious has created a space for thousands of South Africans to gather with family and friends, enjoy a huge variety of different food and experience standout local and global performers. The next chapter builds on that legacy while expanding the platform for the people behind the magic: artists, chefs, entrepreneurs, designers and other creative voices shaping the country’s cultural future.

“Delicious has always been about bringing people together through the universal languages of food and music,” says Tom Pearson-Adams, CEO & Founder of Delicious Festival. “We are thrilled to welcome Absa to the Delicious family at such a defining moment in the festival’s journey.”

“Absa understands that culture is not simply something we consume; it is something we create, share and pass on. With its support, the Absa Delicious Festival in partnership with SABC can build on what people already love while creating more opportunity for African talent, businesses and stories to flourish. Together, we are creating a festival that South Africans can continue to proudly call their own.”

Themba Gwejela, Group Executive for Corporate Affairs and Marketing said, “The SABC is proud to partner with Delicious Festival as the official broadcast partner of one of South Africa’s most exciting celebrations of food, music, and culture. This partnership gives us an opportunity to take the delicious experience beyond the festival grounds and into homes across the country through our television, radio, and digital platforms, including SABC+.

Food and music have a unique ability to bring people together, and Delicious Festival captures that spirit beautifully. As the public broadcaster, our role is to connect South Africans with experiences that reflect who we are, what we love and how we celebrate. We are excited to amplify the festival across our platforms and give audiences everywhere a taste of the delicious experience.”


The sponsorship forms part of Absa’s broader investment in platforms that elevate talent, craftsmanship, culture and connection. These include the Absa Champagne in Africa Festival, Absa Jazz Sessions at Marble, the Absa RUN YOUR CITY Series and the Absa L’Atelier Art Competition amongst others.

“The Absa Delicious Festival in partnership with SABC is a natural extension of our commitment to enabling the possibilities within people’s lives,” Mbhele adds. “It gives us an opportunity to celebrate African excellence, connect people to the passions that inspire them and ensure that more stories are given the audience they deserve. Because every story matters — and this is one South Africans will write together.”

The countdown to the inaugural Absa Delicious Festival in partnership with SABC 2027 has begun. Follow Absa on social media at @Absa.SouthAfrica, visit the Absa website and follow Delicious channels for exclusive announcements, artist reveals, ticket information and festival news.

Categories
Our Voices

Meeting the New Demands of Pension Fund Custody in Africa

Meeting the New Demands of Pension Fund Custody in Africa

scroll for more

By Mosetsana Mahlafunya, Group Head of Absa Investor Services and Francinah Madise, Sector Head, Public Sector (Client Coverage) at Absa CIB

The appointment of Absa as Master Custodian to South Africa’s Government Employees Pension Fund (GEPF) has understandably attracted attention within institutional investment circles. The GEPF is not only Africa’s largest pension fund but one of the continent’s most significant pools of long-term capital. The mandate itself is noteworthy for its scale, but perhaps more interesting is what it says about the direction of travel for pension funds and custody services across Africa.

Pension funds on the continent, and similarly around the world, were historically largely domestic in character, both in terms of where savings originated and where those savings were ultimately invested, which meant the relationship between those funds and their custodians was built on a relatively clear set of expectations. Assets needed to be safeguarded, transactions settled, records maintained, and income collected, and that arrangement worked because it reflected the realities of the pension industry at that particular stage of its development.

Over time, however, these funds have grown into some of the largest institutional investors in their respective economies, overseeing pools of capital that would have been difficult to imagine a generation ago. According to the OECD, pension assets in Namibia exceeded the size of the country’s economy, while Botswana, Namibia and South Africa all recorded pension assets-to-GDP ratios above both the African and OECD averages.

The picture is far from uniform, with many markets still at much earlier stages of development, but the broader trend is difficult to ignore: as these funds grow, they become more complex.

Diversification is perhaps the defining theme in pension fund investing at present, as funds look beyond traditional allocations to government bonds and listed equities and into infrastructure, private markets, real estate and other alternative assets. In a number of markets, that search for diversification also extends beyond borders, with funds allocating a portion of their capital to regional and international opportunities in pursuit of broader exposure and risk-adjusted returns. There has also been considerable work around digital assets, which remain a very small part of the pension landscape but have nevertheless become a subject of evaluation by regulators and investment managers as the industry considers how emerging asset classes may fit within long-term investment frameworks.

Sustainability has also moved much closer to the centre of investment decision-making, with environmental, social and governance considerations now routinely incorporated into how and where capital is allocated. That conversation intersects with another, namely the role pension capital can play in supporting infrastructure and broader economic development. The opportunity here is significant, but so too is the responsibility. Pension funds ultimately exist to protect the long-term interests of their members, which means development objectives must always be weighed against fiduciary obligations and investment risk.

A pension fund operating across a broader range of investment opportunities and obligations places very different demands on the institutions responsible for supporting those activities. The custody function has always been an important part of that equation, but the role goes well beyond the administration of assets now.

Custodians are responsible for safeguarding investment assets, settling transactions, maintaining investment records, managing cash movements linked to investments and providing the reporting that allows funds and their stakeholders to understand what is taking place across often substantial and complex portfolios. Alongside this is an equally important responsibility around governance, oversight and regulatory compliance, helping ensure that assets are accounted for correctly and that investment activity is conducted within the frameworks established by regulators and fund mandates.

Much of this work takes place behind the scenes, which is perhaps why it receives less attention than investment performance or asset allocation. Yet for pension funds operating at scale in Africa, strong custody infrastructure plays an important role in maintaining confidence in the system. The ability to provide accurate information, support informed decision-making and maintain operational stability across large and complex portfolios has become a critical component of modern pension fund administration.

The assumption has often been that the largest and most complex custody mandates should be entrusted to international institutions. Yet domestic custody capabilities across Africa have developed considerably over time, supported by sustained investment in technology, infrastructure, governance and operational expertise. The GEPF mandate is one example of that shift. Absa’s appointment is not simply a single-bank development, but a useful marker of how African financial institutions are increasingly being expected to support custody, reporting, operational resilience and governance requirements at a scale once more commonly associated with global custodians.

Categories
Our Voices

Why Edutainment may be the future of Consumer financial education

Why Edutainment may be the future of Consumer financial education

scroll for more

By Dr Reaan Immelman, Head of Financial Literacy, Education at Absa

Is consumer financial education actually working in South Africa?

As someone deeply passionate about financial empowerment this is one of the burning questions I find myself constantly pondering.

Every year, the financial services sector commits a substantial investment to Consumer Financial Education (CFE) initiatives. Corporates regularly supplement these efforts with internal financial wellness programs, webinars, and advisory workshops. On paper, the country has never had access to more financial literacy content.

Yet, when we look at the actual data, it gives us pause for thought and reflection. We have a negative national savings rate – in other words the average household spends more than it earns. The household debt to income ratio sits at around 60% – meaning for every R1 earned, 60c is spent on debt servicing and the estimation is that less than 10% of South Africans can afford to retire.

We also know that there is a clear link between financial stress and your overall wellbeing.

If we bring all of these factors together, in pursuit of financial peace of mind, it’s no wonder some people consider putting their money under their mattresses.

This may be a bit tongue-in-cheek, but we really do need to interrogate where we are going wrong with managing our finances.

It is critical to acknowledge that even with the best financial ambitions, we face some very real structural realities around unemployment and a cost-of-living crisis which is biting across the world. I don’t discount that and more financial education isn’t going to change what is happening in the global economy.

Rather, our question is around how we are developing good financial habits and behaviours. More specifically, why we are struggling to get the basics right.

There was some research conducted by the industry which pointed out that South Africa’s financial literacy score was around 52 out of 100. Down from 55 on the previous reading. How can it be going down if we are spending so much time and energy driving these financial literacy campaigns?

In my view, it has a lot to do with the barrier of silence around money and or the pressure of  #LivingTheBestLife,  as the youth so often say.

Part of the issue is that conversations about money in South Africa remain uncomfortably taboo. Discussing debt, budget shortfalls, or financial anxiety is hard – especially in a culture increasingly shaped by digital peer comparison.

On social media, feeds are dominated by curated highlights of people showing their new cars, career milestones, luxury vacations, and high-end lifestyles. This digital pressure valve distorts reality, making individual financial struggles feel like personal failures rather than shared systemic challenges.

This becomes an important social challenge and imperative. Financial  confidence is built through two important elements: financial literacy, helping people make smarter everyday money decisions, from budgeting for life’s biggest moments to managing unexpected expenses, and secondly financial security – helping people recognise scams, protect their money and keep their personal information safe.

This is why we are adopting a new approach when it comes to financial education initiatives. We want to meet our audiences where they are consuming the content that matters.

The question is how?

If traditional lectures, brochures, and corporate workshops aren’t driving behavioural change, how do we make financial literacy resonate? This is where my finance and marketing brains go into overdrive.

Media consumption habits clearly show that people are more receptive to short-form, mobile-ready video content. This tells us a lot about the type of content we should be developing. Instead of formal instruction, we need to leverage narrative entertainment, like Micro-Dramas.

As one of the world’s fastest-growing digital entertainment formats, micro-dramas deliver compelling, serialized stories in short vertical episodes designed explicitly for cellphones. This form of story-telling is often characterised with high-impact content, built with the intention of making the viewer come back for more.

In our case, we have developed a series called “For Better Or For Whatever” which we are launching in September 2026 and we are intrigued to see how it is received. Distributed across platforms like TikTok, YouTube shorts, and Instagram reels, which align with modern media consumption habits: the series is easy to watch during a commute, simple to share, and inherently bingeable.

This might not replace a daily fix of your favourite long format series, but here is why I think “For Better Or For Whatever” might actually get some traction and mass appeal.

The storyline is centred around two South African families brought together by a major wedding where virtually nothing goes according to plan. Packed with local humour, cultural nuance and heart, the series does not preach interest rates or balance sheets. Instead, it unpacks how money quietly shapes family dynamics, personal relationships, and life’s major milestones. A relatable day in the life of an average family.

By watching characters navigate financial pressure points on screen, audiences are prompted to reflect on their own spending and saving choices through entertainment rather than instruction.

Importantly we have recognised that information alone will not change behaviours, we have to deliver content to where people are feeling confident around engaging with content. Finances are such a personal topic and we believe this will be a great way to incentivise people to start having these discussions in a safe space.

It is no secret that economic conditions globally are tough right now. Household budgets are stretched, and financial anxiety is at an all-time high. To create genuine financial resilience, we must demystify money conversations and strip away the shame associated with financial stress. By breaking down barriers and adopting fresh, engaging communication channels, we can equip you with the tools and confidence to make informed, realistic decisions about how to save, invest, and spend.

Categories
Our Voices

Women Now Make Up Majority of Young Property Investors, Absa HSI Finds

Women Now Make Up Majority of Young Property Investors, Absa HSI Finds

scroll for more

Absa’s latest Homeowners Sentiment Index (HSI) shows that more women are building property portfolios in South Africa, with the strongest growth coming from younger buyers.

Among investors who own three or more properties, women accounted for 48,1% in the second quarter of 2026, up from 46,7% in the same period two years ago. Women also now make up the majority of property investors aged between 25 and 34 at 51,8%.

These figures point to a broader change in female representation in the property market, with women gaining ground beyond homeownership and into property investment. The fact that younger women now make up the majority of investors in their age group suggests this could become an even more significant feature of the market over time.

“What we have seen is that consumers and investors are well aware of the ongoing economic and political shifts around them, and they are cognisant that these changes will influence their buying power and the financial commitments of homeownership. Property ownership and investment are still desired goals, but the decision to enter the market is being viewed more carefully and strategically,”
said Nondumiso Ncapai, Managing Executive: Home Loans Absa Group.

Overall, consumer confidence in South Africa’s property market decreased slightly by one percentage point to 87% in the second quarter of 2026. The softer reading comes as uncertainty around interest rates, the economy and the political environment weighs more heavily on decisions to buy, invest in and renovate property.

Confidence declined across all of the HSI subindices over the quarter, with buying sentiment falling by 7 percentage points, renovating by 6 points, investing by 5 points, renting by 4 points and selling by 3 points. The decline in buying sentiment was the most significant, marking the largest quarterly drop since Q4 2022. Respondents pointed to the high cost of living, concerns about the economy, elevated interest rates and high property prices as the main factors holding back confidence.

“Affordability is the single biggest constraint on property ownership. Respondents repeatedly link the difficulty of buying and keeping property to high costs relative to income. Many cannot afford deposits, bonds and rising ongoing costs such as rates, levies, utilities and maintenance. This is leading some to delay or abandon buying, downscale or sell, even though they still see property as desirable,”
said Ncapai.

The HSI also found that the broader economic environment is weighing on property decisions, with consumers concerned that economic instability could keep interest rates high or push them higher. Respondents linked bond repayments, possible rate increases and strict lending criteria to greater financial stress and a higher perceived risk of entering or staying in the market. Crime and area safety were also cited as major considerations. Respondents associated high crime levels with lower property values, difficulty selling and higher security costs, with many favouring secure estates or better-policed areas when considering where to buy.

“Many South Africans still see property as a safe long-term investment with the potential to appreciate in value and build wealth. But that value is now being judged more carefully against factors such as location, demand, political confidence, service delivery and expectations for the future,”
said Ncapai.

The Absa HSI is a leading indicator of the overall state of consumer confidence in South Africa’s property market. Launched in 2015, the Index’s overall consumer confidence insight is supported by sub-indices that measure consumer confidence around buying, selling, and investing in property.

To view the full report, visit our Homeowner Sentiment Index site.

Categories
Our Voices

More Buyers Are Entering South Africa’s Luxury Property Market, Absa HSI Finds

More Buyers Are Entering South Africa’s Luxury Property Market, Absa HSI Finds

scroll for more

Absa’s latest Homeowners Sentiment Index (HSI) shows that more luxury properties are being bought in South Africa, with the upper end of the residential market seeing a noticeable increase in activity over the past year. Homes valued above R4,5 million accounted for 5,2% of transactions in the second quarter of 2026, up from 4,0% a year ago, and now make up more than a quarter of the market by value.

Much of this growth is coming from the Western Cape, where luxury properties accounted for 9,9% of transactions during the quarter. This means that almost one in ten properties being bought in the province now falls within the luxury segment.

High-net-worth customers and entrepreneurs are also increasingly using legal entities when purchasing property, often as part of broader wealth planning considerations. Legal entities accounted for 27% of property market activity in the latest quarter, highlighting another feature of how wealthier buyers are approaching property ownership.

“What we have seen is that consumers and investors are well aware of the ongoing economic and political shifts around them, and they are cognisant that these changes will influence their buying power and the financial commitments of homeownership. Property ownership and investment are still desired goals, but the decision to enter the market is being viewed more carefully and strategically,”
said Tshepo Mashashane, Head: Business Strategy and Strategic Communication.

Overall, consumer confidence in South Africa’s property market decreased slightly by one percentage point to 87% in the second quarter of 2026. The softer reading comes as uncertainty around interest rates, the economy and the political environment weighs more heavily on decisions to buy, invest in and renovate property.

Confidence declined across all of the HSI subindices over the quarter, with buying sentiment falling by 7 percentage points, renovating by 6 points, investing by 5 points, renting by 4 points and selling by 3 points. The decline in buying sentiment was the most significant, marking the largest quarterly drop since Q4 2022. Respondents pointed to the high cost of living, concerns about the economy, elevated interest rates and high property prices as the main factors holding back confidence.

“Affordability is the single biggest constraint on property ownership. Respondents repeatedly link the difficulty of buying and keeping property to high costs relative to income. Many cannot afford deposits, bonds and rising ongoing costs such as rates, levies, utilities and maintenance. This is leading some to delay or abandon buying, downscale or sell, even though they still see property as desirable,”
said Mashashane.

The HSI also found that the broader economic environment is weighing on property decisions, with consumers concerned that economic instability could keep interest rates high or push them higher. Respondents linked bond repayments, possible rate increases and strict lending criteria to greater financial stress and a higher perceived risk of entering or staying in the market. Crime and area safety were also cited as major considerations. Respondents associated high crime levels with lower property values, difficulty selling and higher security costs, with many favouring secure estates or better-policed areas when considering where to buy.

“Many South Africans still see property as a safe long-term investment with the potential to appreciate in value and build wealth. But that value is now being judged more carefully against factors such as location, demand, political confidence, service delivery and expectations for the future,”
said Mashashane.

The Absa HSI is a leading indicator of the overall state of consumer confidence in South Africa’s property market. Launched in 2015, the Index’s overall consumer confidence insight is supported by sub-indices that measure consumer confidence around buying, selling, and investing in property.

To view the full report, visit our Homeowner Sentiment Index site.